Thursday, September 04, 2014

The Problem With Index Funds


I was glad to see on Friday someone (Yahoo! Finance Editor-in-Chief, no less) concur with my concerns over the growth of index-based investing strategies (see “One reason I’m worried about the rise of the robo-adviser“). In a piece appropriately titled, “Pride cometh before the fall: indexing edition,” Aaron Task writes:

Was ‘owning the index’ a good idea in 2000, when ~50% of the S&P 500 was in tech?
Was ‘owning the index’ a good idea in 2008, when 40% of the S&P 500 was in financials?
No, of course it wasn’t.
But that’s exactly what you did if you followed an index-based approach. So while index investing is probably better than many of the alternatives that doesn’t mean it doesn’t have its own problems. And being valuation agnostic is probably its biggest problem.
You see when you buy an index fund you put more money into the largest companies in the index and less money into the smallest, regardless of their valuations. So when investors bid tech stocks to the moon and they become the largest component of the index (as in 2000) they carry a larger weight in the index and, in turn, you end up buying a lot of them. In effect, you become greedy when others are greedy rather than becoming fearful, as Buffett would recommend (he also recommends indexing, though, so go figure).
And taken to the extreme, the growing popularity of index-based investing could possibly be the cause of yet another stock market bubble. When a growing class of buyers is willing to continue buying regardless of how high prices rise then valuations can conceivably rise infinitely (Sound familiar? Indiscriminate buying of internet stocks in 2000? Indiscriminate buying of housing in 2007?).
What index-based strategies don’t want you to know is that ‘the price you pay DETERMINES your rate of return.’ Pay too high a price and you literally guarantee yourself horrible returns. Forget owning too much of one sector within the index; was it a good time to buy stocks at all at March of 2000 or October of 2007? Hell, no. Sky-high valuations were a big reason for that. And we may have already reached that point once again (Jesse Livermore recently wrote a wonderful piece on the topic – see “Why is the Shiller CAPE so high?“).
Finally, I personally see the growing popularity of index-based investing as a good thing for individual investors over the long-term but also as a potential contrarian indicator over the intermediate-term.
Aaron again:
The pendulum has swung way too far where everyone thinks all you have to do is index and you’re going to do better [than actively managed funds].
Once the pendulum has swung so far that many investors come to believe that all you have to do is buy the index and it’s all peaches (cap gains) and cream (dividends) then it’s probably time to look out below. I just don’t know if we’re there yet.

Wednesday, September 03, 2014

Is your ‘alternative’ mutual fund a ticking time bomb?


Shutterstock.com
An ‘alternative’ fund sounded like a good idea, but we don’t have a clue what’s in ours.
Most people who own “alternative mutual funds” can’t accurately describe what they’ve got in their portfolio.
The label “alternative” seems to cover countless strategies and, technically, can be applied to anything that falls outside of the mainstream investment categories of stocks, bonds and cash.
But the Securities and Exchange Commission clearly has some concern that what is being marketed to the public as a panacea for making money in volatile, unpredictable markets could also be a hot potato or, worse, a ticking time bomb.
Afraid that investors could see their portfolios blown up by issues they don’t fully recognize or understand, the regulatory agency recently launched a broad examination of alternative funds.
Sources close to the probe say the SEC has been doing “sweeps” at big-name firms (think BlackRock Inc. BLK,+1.12%  and AQR Capital Management), while also tapping some small firms that are new in running hedge-like mutual funds for small investors. The agency is not necessarily looking for or expecting to find wrongdoing, but more seems to want to get a handle on one of the fastest-growing parts of the fund world before the market tests the new products in ways that investors aren’t prepared for.
SEC officials have confirmed that about 30 firms will be examined; the sweeps will include contact with fund board members, trying to determine whether the complexity of these types of funds requires specialized oversight.
Alternative funds have been the hot trend in the fund world for a few years now, with inflows of more than $40 billion in 2013 and about $17 billion more this year, according to Morningstar Inc. The Chicago-based research firm pegged the amount in alternative funds at north of $260 billion last year.
But the “alternative” label means many things to many people.
Typically it describes mutual funds that use strategies traditionally reserved for hedge funds. The category started with long-short, market-neutral and absolute-return strategies, typically funds that use short-selling strategies to generate positive returns even when the market is flat or down. For all the hype, the majority of these funds have proven to be mediocre performers regardless of market conditions.
Today, a lot of the focus is on “liquid alternatives,” which typically means buying illiquid securities — things like private credits and some derivative issues — and turning them into a fund that is “liquid” because it can be bought or sold at any moment on the open market.
But “liquid” may refer to how watered-down and diluted some of the strategies are. It’s also where regulators are nervous, because some of these strategies could fall apart the next time the market experiences hurricane conditions.
“A lot of the underlying investments in these alternative funds will prove problematic in different situations,” said Jeff Sica, chief investment officer at Circle Squared Alternative Investments, a new firm that evaluates issues in the space, but which also is pursuing its own alternative solutions.
Jaffe: Many 2014 predictions were wrong
Marketwatch's Chuck Jaffe points out as the calendar is just hitting the home stretch for the year, it’s time to recognize that virtually everyone who made calculated forecasts for 2014 was wrong.
“If the underlying assets can’t be easily liquidated, there’s a real question of what happens if the market has a problem,” Sica said. “There’s no real liquidity in alternative investments. It doesn’t exist, which is why probably 95% of liquid alternatives funds are useless. … Most are just institutions trying to get on the bandwagon, creating liquid shells; if they were real alternatives, they would not be as liquid as they are.”
Sica and other experts suggest one area of concern would be with private credit, where funds are investing in deals that a typical bond or income fund could not pursue, and suggesting that these private credit deals will deliver income streams of up to 7%.
In the event of an economic meltdown like the financial crisis of 2008, however, there’s no guarantee that the private credit obligations will be met; if panicky investors rush the exits, a fund would now be left trying to unload those private credits to meet redemptions, in a market that is illiquid.
That’s how a mutual fund implodes.
Ultimately, the likelihood of that kind of event is precisely what the SEC is trying to determine, at which point it will determine what kind of actions to take, whether that is stiffer warnings about the risks of the funds, all the way on up to ruling that some of the funds have crossed boundaries and need to be shuttered.
Meanwhile, investors should know at least that alternative funds may fall into one broad category, but they can be unique and individual, meaning it would be a mistake to assume that the risks associated with one fund are the same with the next. Conversely, if alternatives are appealing, experts suggest diversifying and using different funds to share the alternative space in a portfolio.
“Investors may not know what they’re buying, but they should know enough to split their alternative money between a few funds,” said Sica. “Hopefully, there is never a problem that makes any of these funds suffer or vanish, but you should at least invest like problems with alternative funds are possible because, well, they are.”

Tuesday, August 26, 2014

WILL LIQUID ALTS’ PERFORMANCE SUSTAIN FUTURE ASSET FLOWS?


Forget questions about whether liquid alternative funds are here to stay. The surge of inflows to liquid alternative funds suggests that debate is over.
According to McKinsey & Company projections, inflows to liquid alternative funds will reach $900 billion by the end of 2015. That surge is likely coming at the expense of traditional hedge fund investments. 
A study by Barclays Prime Services shows that capital flows into liquid alternatives—also known as hedge-like mutual funds—are outpacing dollars going into hedge funds. Liquid alternatives grew by 43% last year, while hedge fund assets increased by 15%. 
Liquid alternatives are the fastest growing category of ’40 Act structures, even though they comprise a tiny part of the mutual fund industry. Recent data shows that the amount of capital controlled by alternative ’40 Act structures stands at $154 billion, which is just 1% of the entire mutual fund industry. In comparison, hedge funds control $2.7 trillion of capital.
The trend is picking up, particularly as conservative institutional investors like pension funds enjoy ’40 Act funds due to the lack of performance fees, reduced leverage, and beta-centric returns.
The alternative ’40 Act fund universe is in its infancy, with the most mature funds being no more than five years old. While industry watchers like McKinsey predict the industry will continue its exceptional growth, only time will tell if these vehicles can weather a storm.
Rather than debate the permanence of alternative funds, investors should instead ask a more important question:
Do increased liquidity and the lower fees provided by hedge-like mutual funds outweigh the lower expected returns?

OPTIMISM REMAINS HIGH 

The hedge fund versus alternative funds is a false debate thanks to industry advocates who are attempting to promote their products and services. They’ve said alternative funds don’t provide strong returns, aren’t managed properly, or that investor sentiment is dwindling. 
But there is no shortage of optimism surrounding the launch of alternative ’40 Act funds.
“Clearly, this is the fastest growing category,” said Victor Viner, president of V2 Capital, which specializes in volatility-based equity derivative strategies. V2 Capital manages $500 million in a hedge fund vehicle, but is rolling that money over into a ’40 Act fund later this year. 
“We are seeing more funds that can provide liquidity going into the liquid alternatives space for all of the obvious reasons from an investor perspective,” said Viner, adding that the main benefits of liquid alternatives include transparency, liquidity, and lower fees. But despite V2’s move into the liquid alternatives space, Viner warns that most hedge funds cannot be shoehorned into mutual fund structures.
“Not all, and not most, of traditional hedge fund strategies can exist in these structures. In our case, we’re lucky because everything we do and have done for four years falls well within the framework of what can be done in a ’40 Act fund,” said Viner. 
The ’40 Act rules include limiting leverage to 33%, having less than 15% exposure to illiquid assets, and in most cases a prohibition on charging performance fees.
Adam Patti, CEO of IndexIQ, a pioneer in the liquid alternatives space, agrees that only certain strategies will work in a ’40 Act structure. 
“The major hedge fund categories—long/short, market neutral, global macro— can [be] provided in a ‘40 Act fund fairly efficiently,” he said. “Strategies that require a significant amount of leverage won’t work. Strategies that tend to depend on illiquid, arcane asset classes won’t work.”
Instead of having a “one of the other philosophy” when comparing hedge funds and liquid alternatives, investors could see them as complementary products.
“The majority of our assets ($1.4 billion) are in a multi-
advisory product that is basically the S&P 500 of the hedge fund market,” said Patti. “It is designed to give you the risk/return profile of a universe of a hedge fund of funds…. You would use that as a core product in your portfolio and then
go out and find alpha-seeking hedge funds as satellites around it.”

A FALSE SENSE OF SECURITY?

One of key selling points of liquid alternatives is transparency. 
But while transparency may seem like an obvious benefit, Bill McBride, executive vice president at quantitative research and technology specialist Markov Processes International (MPI), wonders whether having access to the underlying investments does any good. 
“The Securities and Exchange Commission (SEC) says investment advisers are fiduciaries and need to verify that a fund is executing its stated strategy based on available data,” explained McBride. “How many advisers can internally price and net the exposures of the thousands of positions (including complex derivatives) in an unconstrained long/short bond fund?”
McBride added that technology to tackle the data issue is rapidly being developed.
“There is room to mature and we think it will happen quickly. Investors will seek advanced systems and analytical techniques to process liquid alternatives’ holdings data, net exposures and grasp a fund’s strategy and potential risks, while managers will seek ways to enhance communication to investors, all potentially facilitated by SEC mandates as attention is increased on this rapidly growing space.”
Patti, who touts transparency, also thinks it is important for advisers and investors to “look under the hood” and get a better understanding of what is in each product.
“Advisers don’t know what they are getting and that’s a big problem,” said Patti, who believes educating advisers and investors should be a top priority for the industry as a whole.
Andrew Ross, associate director of Pacific Alternative Asset Management Company (PAAMCO), which has approximately $9 billion in discretionary assets under management, points out that transparency is not unique to the ‘40 Act fund structure. 
“Institutional investors can receive transparency and independent oversight of their hedge fund investments in their traditional private placement hedge fund investments,” said Ross. “Some institutional investors are already receiving all of their positions on a monthly basis with a less than 30-day lag, which is far superior to the required 60-day lagged, quarterly transparency of liquid alternatives.”
Of course both pale in comparison the managed futures, which offers daily transparency in the typical managed account structure. 
PAAMCO, specializes in fund of hedge fund structures and caters almost exclusively to institutional investors, and has no plans to enter the ’40 Act space. 
“At this point we do not feel that this product is appropriate for institutional investors and we do not have a view on its suitability for retail investors,” said Ross.

LIQUIDITY AND SYSTEMIC RISKS LOOM

While liquidity is usually touted as a benefit for investors, McBride feels that just like transparency, investors may be relying too much on the idea of it rather than the reality.
“How can you have daily liquidity in a $4 billion equity long-short fund?” McBride asked. “The senior hedge fund managers I have spoken with have expressed serious concern that large liquid alternatives vehicles could have trouble raising cash very quickly if executing a truly hedge fund like strategy.”
The SEC is also voicing its concern. The regulatory agency has already begun investigating 25 liquid alternative funds on structural matters of leverage and daily liquidity and the associated risks. PAAMCO’s Ross also believes that promises of daily liquidity are overstated.
“The daily liquidity of liquid alts can create ‘bank-run’ risks because of the asset-liability mismatch problem created. Although liquid alternative funds have stated daily liquidity, current rules actually allow these funds to operate without the ability to liquidate all underlying investments in a day,” explained Ross. “Although ‘bank-run’ risk exists in all mutual fund structures because the investors in them have daily liquidity, the risk is heightened with liquid alts due to the relative novelty of the strategy to the retail investor.”
The regulatory efforts aren’t likely to end just on concerns about liquidity. In fact, liquidity fears will likely generate expanded efforts by agencies to dig deeper into how these funds generate returns, their risk management strategies and their marketing practices.

LIQUIDITY PENALTIES ON PERFORMANCE

Despite concerns about increased regulation in the space, liquid alternative funds provide one big benefit that isn’t going unnoticed. Lower fees. 
The question investors must ask is:  
Will the lower fees be enough to offset the difference in
performance?
One recent study by advisory firm Cliffwater found a 1% drag on performance for hedge funds going into ‘40 Act structures. But that isn’t shaking faith in these funds.
“Call it the liquidity penalty,” said Viner, who despite the potential lag in performance believes the lower fees will more than offset gains that can be made in a hedge fund vehicle.
“A lot of managers are highly correlated to the S&P and they are producing beta, but they are charging 2% management fee and 20% on profits,” said Viner.
Over time, one can expect that alternative funds and their hedge fund cousins will be debating the merits of their structures and ultimately their performance. For now, the jury remains out. As for solid, historical evidence on the long-term returns of hedge funds versus those of liquid alternatives, there isn’t any.
As the industry takes shape, time will tell which side is able to earn the bulk of new asset flows. For now, it’s up to investors and the media to do the diligence.

Wednesday, August 20, 2014

Pershing Sq. Quarterly Letter (+25% YTD)

How The Largest Actively Managed Mutual Funds From 15 years Ago Performed

You can't go long without reading an article about the death of active management. Somewhere in a discussion like that you will also hear that the larger a fund gets the more likely it is to under-perform. My purpose of this post is not to get into either of those issues but I thought it would be interesting to take a glimpse back in time to the largest funds of 1999 (15 years ago).


For this exercise I decided to screen for the largest actively managed funds 15 years ago (8/1999) which had the S&P 500 as their prospectus benchmark. The top 10 results looked like this

So how did they do? Were they too big to outperform?
Indeed, the largest fund did manage to under-perform. However, as a whole, these large funds did quite well. Over the last 15 years the largest 10 funds which were benchmarked to the S&P 500 managed to return an average of 5.47% compared to 4.47% for the S&P 500.

What's also interesting is that despite the fact that I compared them all to their prospectus benchmark of the S&P 500, a few of them tend to have a known growth tilt (Vanguard Primecap, Growth Fund of America, Fidelty Contrafund) but they all managed to significantly beat the S&P 500 despite the fact that growth significantly underperformed the S&P during this time (Russell 1000 Growth returned only 3.18% compared to 4.47% on the S&P 500).

NO BUBBLE, NO PROBLEMS?

There’s a recurring theme emanating from nearly every permanently bullish pundit right now. I’m sure you’ve heard it. It goes something like this: “I was around in 1999-2000. You have no idea how crazy it was back then. We are nowhere near that level of mania today. We therefore have much, much further to go.”

On its face, it seems like a reasonable statement. After all, 2000 was the peak of the greatest U.S. stock market bubble we have ever seen. A chart of the CAPE ratio (or Shiller P/E) illustrates just how stretched valuations were back then and how we’re  still far from such levels today.
bubble1
The issue, though, is that every Bull Market doesn’t go through a 2000-like bubble before it becomes a problem. Since 1929, there have been twenty Bear Market declines in the S&P 500 (roughly one every 4-5 years). Only one of these was preceded by our collective definition of a bubble.
Bears4
Therefore, to argue that stocks are a good buy today and can’t go down because they have not yet reached the extremes of the greatest bubble in history is to argue two things. First, that there is a high probability of a similar bubble occurring, and second, that you have the ability to time your exposure to the bubble to insure that you get out before it inevitably bursts.
Today, many would argue on the first point that the probability of a similar bubble occurring is indeed high. After all, the Federal Reserve seems to want this outcome as they have maintained the loosest monetary policy in history five years into the recovery. If market participants are correct and the Fed does not raise rates until next July, it will be six and half years of zero percent interest rates at that point. Investors tend to do highly irrational things when money is this cheap. Thus, while I would not go as far as to say the odds of another dot-com like bubble are high, we cannot entirely rule it out.
What I would argue strongly against, though, is ability of the majority investors to effectively time their exposure to such a bubble. If history is any guide, most investors will not fare well as they have a strong tendency to buy high and sell low.
As we are approaching the 90th percentile of historical valuations (CAPE above 26), make no mistake about it, investors getting in here with hopes of another 1999-2000 bubble are indeed buying high. No, not as high as 1999-2000, but high enough where they should be expecting significantly below average returns over the next 7-10 years.
bubble3
Bottom Line
The permanently bullish camp is correct. It is not 1999-2000.  If that makes you feel better about buying stocks here, great, but it is not an argument based on logic.  As we saw in 2007, just because it is not a once in a hundred years bubble, it doesn’t mean there is no risk of a significant market decline. It also doesn’t mean that valuations are compelling and that investors should be expecting above average long-term returns from here. They should not. Something to think about the next time someone tells you a story about how this mania pales in comparison to the epic dot-com bubble.

What makes Buffett a great investor? Is it the intelligence or the discipline?


I thought this excerpt from Warren Buffett’s 2011 interview in India was relevant to not only investing but also decision making. A member of the audience says to Buffett: “As we all know, you are an extremely intelligent person. At the same time, you are very disciplined with your investing approach. What makes Warren Buffett a great investor? Is it the intelligence or the discipline?”
Here is Warren’s response.
Warren: The good news I can tell you is that to be a great investor you don’t have to have a terrific IQ.
If you’ve got 160 IQ, sell 30 points to somebody else because you won’t need it in investing. What you do need is the right temperament. You need to be able to detach yourself from the views of others or the opinions of others.
You need to be able to look at the facts about a business, about an industry, and evaluate a business unaffected by what other people think. That is very difficult for most people.
Most people have, sometimes, a herd mentality which can, under certain circumstances, develop into delusional behavior. You saw that in the Internet craze and so on. I’m sure everybody in this room has the intelligence to do extremely well in investments.
Moderator: They’re all 160 IQs.
Warren: They don’t need it. I’m disappointed they haven’t sold off some already. The 160s won’t beat the 130s at all necessarily. They may, but they do not have a big edge. The ones that have the edge are the ones who really have the temperament to look at a business, look at an industry and not care what the person next to them thinks about it, not care what they read about it in the newspaper, not care what they hear about it on the television, not listen to people who say, “This is going to happen,” or, “That’s going to happen.”
You have to come to your own conclusions, and you have to do it based on facts that are available. If you don’t have enough facts to reach a conclusion, you forget it. You go on to the next one. You have to also have the willingness to walk away from things that other people think are very simple.
A lot of people don’t have that. I don’t know why it is. I’ve been asked a lot of times whether that was something that you’re born with or something you learn. I’m not sure I know the answer. Temperament’s important.
Moderator: That’s very good advice, to be detached from all the noise. You shouldn’t go with the herd.
Warren: If you don’t know the answer yourself don’t expect somebody else to tell you. If you don’t know the answer yourself and somebody else says they know the answer, don’t let that fact push you into coming to a conclusion about something that you don’t know enough to come to a conclusion on.
Stocks go up and down, there is no game where the odds are in your favor. But to win at this game, and most people can’t, you need discipline to form your own opinions and the right temperament, which is more important than IQ.
Pascal said it best: “All men’s miseries derive from not being able to sit in a quiet room alone.”
Warren: If you look at the typical stock on the New York Stock Exchange, its high will be, perhaps, for the last 12 months will be 150 percent of its low so they’re bobbing all over the place. All you have to do is sit there and wait until something is really attractive that you understand.
And you can forget about everything else. That is a wonderful game to play in. There’s almost nothing where the game is stacked in your favor like the stock market.
What happens is people start listening to everybody talk on television or whatever it may be or read the paper, and they take what is a fundamental advantage and turn it into a disadvantage. There’s no easier game than stocks. You have to be sure you don’t play it too often.
You need the discipline to say no.
Ajit: The discipline to say no, if you have that and you’re not willing to let people steamroll you into saying yes. If you have that discipline, that’s more than 50 percent of the battle.
Warren: Don’t do anything in life where, if somebody asks you the reason why you are doing it, the answer is “Everybody else is doing it.” I mean, if you cancel that as a rationale for doing an activity in life, you’ll live a better life whether it’s in the stock market or any place else.
I’ve seen more dumb things, and sometimes even illegal things, justified (rationalized) on the basis of “Everybody else is doing it.” You don’t need to do what everybody else is doing. It’s maddening, during the Internet craze when the bubble was going on.
Here’s your neighbor who’s got an IQ of 50 points below you, and he’s making all this easy money and your wife is telling you “This jerk next door is making money, and you’re smarter than he is. Why aren’t you making money?”
You have to forget about all those things. You have to do what works, what you understand, and if you don’t understand it and somebody else is doing it, don’t get envious or anything of the sort. Just go on and wait until you find something you understand.
From this video

Thursday, July 31, 2014

The Case for Careful Analysis of Nontraditional Bond Funds

As the end of the 30 year bond bull market begrudgingly gives over to the consensus-expected rate rise, investors’ persistent worries about the impacts of falling bond prices on their portfolios have provided great opportunity for asset managers to aggressively market and/or launch “nontraditional bond” funds. Unlike core or intermediate term bond funds, which typically benchmark their asset classes, duration and performance to the Barclays U.S. Aggregate Bond Index, nontraditional bond funds generally seek to limit interest rate exposure in an effort to preserve capital in the event of higher yields and tightening monetary policy.

Likely helped by 2013’s “Taper Talk” rate rise, the industry’s marketing of these funds and rotating client assets from core bond funds has been very successful. The Morningstar Nontraditional bond category has nearly quadrupled in total number of funds over the past five years from 25 unique funds to 84 as of the start of June. This growth is even more evident when looking at assets. The universe has seen heavy and rapid inflows, more than doubling total AUM in the past 18 months from $68 billion at the end of 2012 to current aggregate AUM in excess of $145 billion. Indeed, Morningstar has deemed nontraditional bond funds’ growth rate “blistering”; over the past year, the group has gathered more assets than any Morningstar category besides Foreign Large Blend (International Equity). Comparatively, the Intermediate Term Bond category has seen a decline in the number of funds and assets, with 17% fewer funds at the end of May as there were five years ago and a 10% decrease in total category assets over the past year due to outflows.
Often used interchangeably with the label “unconstrained” bond funds (as well as “alternative” and/or “long/short”), the general principle (and hook) is that nontraditional bond managers have the flexibility to 1) invest in nearly any fixed income market, 2) make tactical allocations independent of benchmarking and 3) maintain the ability to take both long and short positions. In particular, these managers generally have more flexibility on duration management – including the aforementioned freedom to be short rates – an attractive quality as investors brace themselves for inevitable rate increases.
Despite their popularity, some feel that these funds are simply trading rate risk for credit risk in the form of high yield and emerging markets debt. With tighter correlations between low quality credit and equities, such credit risk doesn’t quite match the conservative stance many investors seek in their fixed income allocations. Debate of the role of such investments in a portfolio setting aside, both retail and institutional investors are increasingly opting to gain alternative exposure through a 40 Act structure, making the numerous (and varied) new nontraditional bond offerings an object of intense attention.
Against this backdrop, we used a quantitative lens to examine some of the characteristics of funds in the Nontraditional Bond category, looking to 1) better understand the level of homogeneity or heterogeneity in behavior and strategy, 2) evaluate some of the common risks exhibited by the category and 3) verify the perception that such funds provide lower duration risk, potentially, at the cost of higher credit risk.
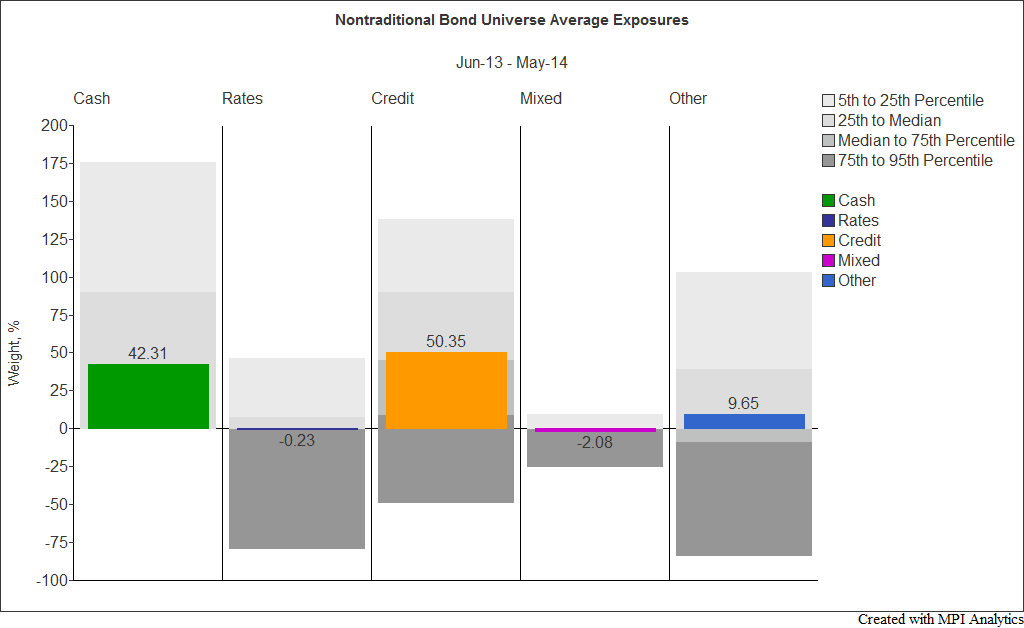
There are 58 distinct, active funds in the Nontraditional Bond category with at least 1 years’ worth of data as of the end of May 2014.[1]  We used MPI’s proprietary Dynamic Style Analysis (DSA) and weekly net asset values to identify the set of factor exposures that best replicate each funds’ performance over the past year. Please note that these “factor exposures” are the result of a purely quantitative analysis and are not based on actual holdings.[2]  The results can be seen in the chart below:
PeerAvg_sml
For simplicity in reporting, each vertical section of the graph above represents a macro basket of underlying sub-factors.  For example, the “Rates” basket includes US government bonds, the “Credit” basket high yield bonds, “Mixed” includes investment grade corporates, while the “Other” category includes those assets which are comparatively insensitive to the other baskets[3], including short term bonds and issues from other developed countries.  Please note that “Cash” may not always be interpreted literally; it may also represent either reduced volatility (in the case of estimated long positions) or excess volatility (in the case of estimated short positions) or else some other form of leverage.
At first glance, it seems that the general perception is correct – the nontraditional bond universe, on average, 1) exhibits very little exposure to the most rate-sensitive factors, 2) appears to have its highest exposure to credit sensitive factors and 3) displays long exposure to less rate-sensitive alternatives in the “Other” basket.
Looking past the average, however, the range of results indicated by the dispersion in the universe is extraordinarily large. Half the funds appear to have positive exposure to rate-sensitive assets, while the bottom quartile shows estimates ranging from 0% to a short position of around -80%.  Similarly, long credit exposure (high yield) ranges from 0% to over 135% for three quarters of the funds, yet a significant minority have short exposure estimates.This is clearly not a homogenous group, investing in a similar fashion.
The advantage that the fund managers may have in the ability to invest anywhere to execute their investment thesis and view on rate risk appears to be a distinct challenge for fund buyers in analyzing the funds.
Using MPI’s proprietary measure of predictability, Predicted R-Squared[4], we find the median value for the group is 72%. From a quantitative modeling standpoint, this is a level more akin to a group of absolute return hedge funds than bond mutual funds. This should give investors and analysts pause. The observed value indicates that while a good proportion of the average funds’ returns can be reliably explained by the factors used, there are likely a number of missing or extraneous factors when analyzed on a fund-by-fund basis.  This is not surprising as we used a set of generic factors as explanatory variables where the actual exposures could be quite specific and broad given the funds’ unconstrained approach. It is, however, an additional indicator of the disparity in investment approaches within the group.
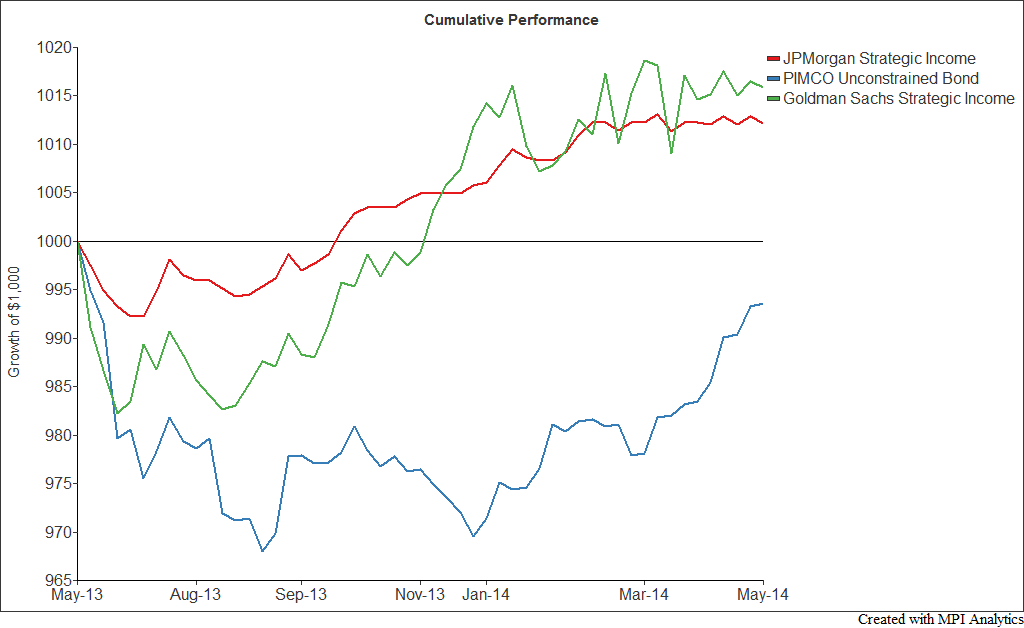
Looking at some representative funds, the impression of heterogeneity is reinforced.  The three largest funds in the category by AUM are Goldman Sachs Strategic Income A (GSZAX, +$24 billion), JP Morgan Strategic Income A (JSOSX, +$26 billion) and PIMCO Unconstrained Bond Inst (PFIUX, +$22 billion).  The funds’ cumulative returns for the past year are shown below.  The path of their returns indicates significantly different investment approaches.  The average weekly correlation between the three funds over the past year is 42%.  By comparison, the average correlation between the largest three Intermediate-term bond funds (by AUM) is 93%. – the top three include industry-leading active managers Jeffrey Gundlach’s DBLTX and Bill Gross’ PTTRX, as well as the Barclays Capital U.S. Aggregate Bond Index tracking Vanguard Total Bond Market Index Inv (VBMFX).
Growth_sml
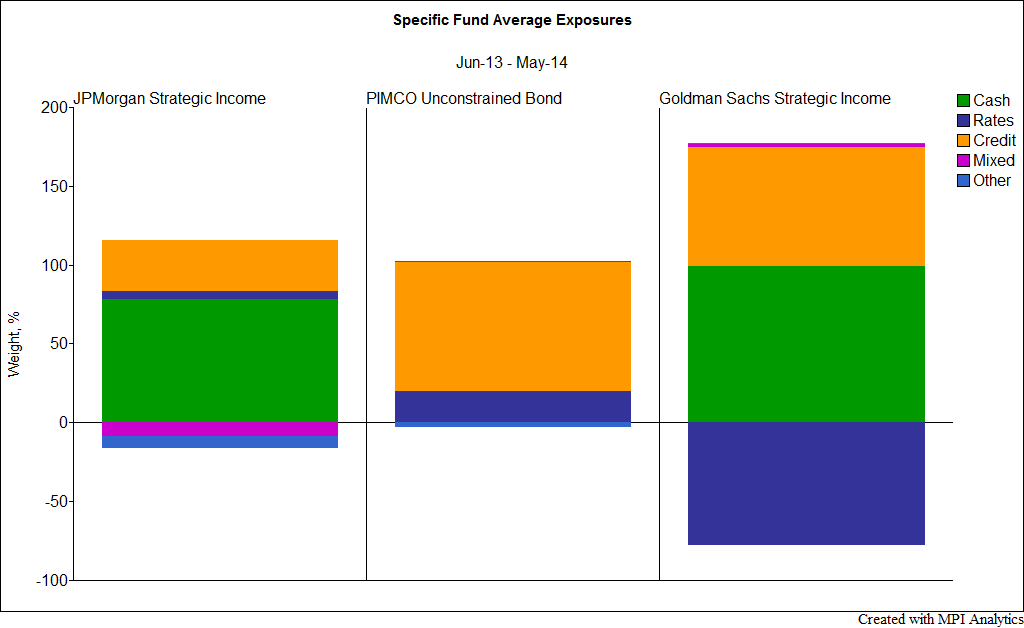
Looking at the three funds’ average exposure estimates, we can see just how dissimilar they appear in a purely quantitative replication of their performance.  Please note that the generic factors used on these funds are the same as those used on the universe above and are unlikely to be the optimal mix for any one fund indvidually.  Regardless, as with the fund universe , the disparity in results strongly indicates that these funds are not comparable on any but a nominal basis and require greater care on the part of investors when selecting and monitoring.
IndivAvg_sml
All three indicate long credit exposure, but in quite different proportions. It is also important to understand the perceived net exposures of the funds. GSZAX appears to have exposure to that which concerns most category critics – short rate-sensitive assets and long credit sensitive, with little net market exposure. JSOSX’s net market exposure is estimated at only about 20%, while PFIUX[5] appears to have full market exposure.
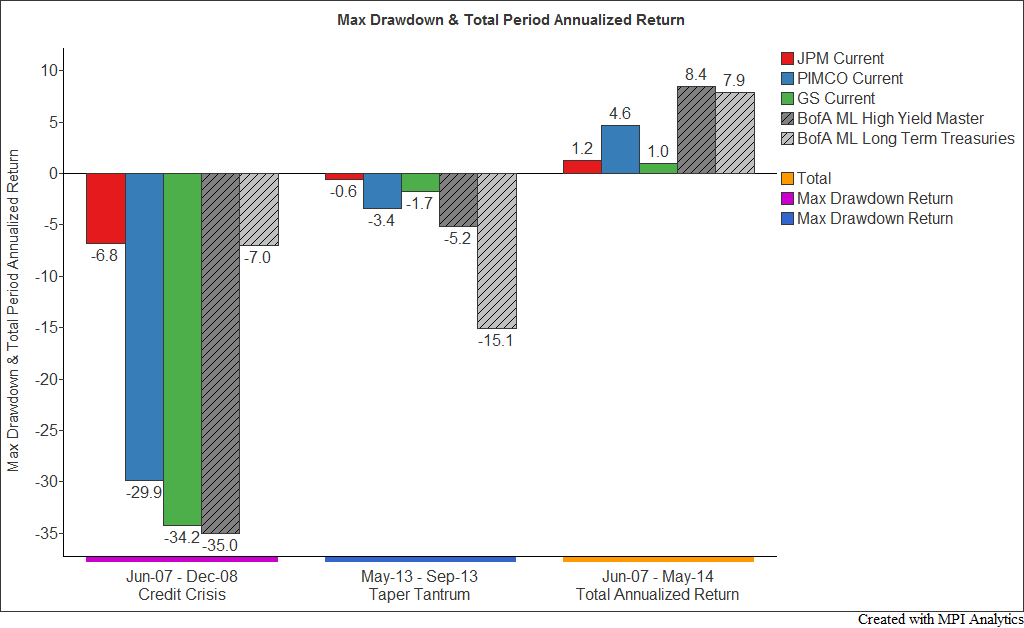
What could these differences mean to investors from a risk perspective? Seeking to answer this question, we tested the current (as of May 30, 2014) exposures for each of the funds and evaluated the replicating (dynamic beta) portfolios’ performance in terms of max drawdown return during two recent periods of stress, the Credit Crisis (June 2007- Dec. 2008) and the Taper Tantrum (May-Sept. 2013).  For reference, two passive indices are included as benchmarks; the BofA ML High Yield Master II Index, and the BofA ML Treasuries index with maturities of 10+ years.
Scenario_sml
Our analysis of all three funds indicates reduced sensitivity to rate changes in 2013, although to different extents.  The JP Morgan Funds shows effectively none, while the PIMCO fund retains at least some rate exposure. In terms of credit risk, again the JP Morgan fund appears to have very little – while the PIMCO fund and Goldman Sachs funds seem to take on a considerable amount. This is just an exercise, of course, and given the funds’ (varying) tactical mandates an investor shouldn’t expect the portfolio to remain stagnant in times of stress.[6]With 2014’s surprise broad bond rally YTD, particularly to long duration government bonds, it is worth noting the varying impacts on current portfolios of an intense “flight-to-quality” period, exemplified here by the Credit Crisis.
Nontraditional bond and unconstrained bond are fuzzy labels, encompassing a considerable range of investment strategies, mandates and risk exposures. This blurring of lines over a fresh-faced, fast-growing group of heterogeneous (and let’s not forget expensive) offerings renders analysts and advisors unable to rely on either category or label to know how to fairly evaluate funds in this ballooning area. Rather, individual manager analysis and the use of smaller, highly targeted peer groups (when possible) should be key in choosing a fund, and determining its role in a portfolio. This is animportant moment for asset managers too. With assets flowing to these offerings,providers must realize the importance in educating investors on the nature of these (typically) new products and their role within a portfolio orientation, as well as the opportunity to differentiate their offering(s) from an increasingly crowded pack.

[1] Implying over 30% of funds in the category have track records less than 12 months at the time of the analysis.
[2] DISCLAIMER: MPI conducts performance-based analyses and, beyond any public information, does not claim to know or insinuate what the actual strategy, positions or holdings of the funds discussed are, nor are we commenting on the quality or merits of the strategies. This analysis is purely returns-based and does not reflect insights into actual holdings. Deviations between our analysis and the actual holdings and/or management decisions made by funds are expected and inherent in any quantitative analysis. MPI makes no warranties or guarantees as to the accuracy of this statistical analysis, nor does it take any responsibility for investment decisions made by any parties based on this analysis.
[3] Which is not to say they don’t have their own risks.
[4] Beyond simple fit as indicated by R2, Predicted R2 is a cross-validation measure of the predictive value of the analysis.
[5] Bill Gross took over the management of the fund in December 2013 from Chris Dialynas and made substantial changes to the portfolio.  Therefore the average exposures are unlikely to be representative of the current. For more, see: http://www.bloomberg.com/news/2014-03-05/pimco-overhauls-unconstrained-fund-as-gross-takes-control.html
[6] All three funds were operational for the Taper Tantrum period and JSOSX and PFIUX were live for a portion of the Credit Crisis period tested, launching in Q4 and Q3 of 2008, respectively. (both funds’ performance through the heavy down market indicates low net credit exposure)

Sunday, July 27, 2014

THE FED PRISONER’S DILEMMA: SELL NOW OR KEEP DANCING?


“When the music stops, in terms of liquidity, things will be complicated. But as long as the music is playing, you’ve got to get up and dance. We’re still dancing.” – Chuck Prince, July 10, 2007
[Joe Kernen: You have been on Squawk Box and said as long as -- you sound like Chuck Prince. You're still dancing now basically. Until they raise rates you're going to dance, right?
Stan Druckenmiller: First of all, I'm not like Chuck Prince because I can get out. I am still dancing, but Chuck Prince and the Fed, if they're wrong, cannot get out. I can get out in a week.] – CNBC, July 17, 2014
Some of you may be familiar with game theory and the famous example of the Prisoner’s Dilemma. In the game, two members of a criminal gang are arrested, imprisoned, and isolated. They have two options: 1) cooperate with one another (stay silent), or 2) betray one another (testify that the other committed the crime). The various payoffs for each decision can be seen below.
PD1
The dilemma is as follows. From a purely self-interest perspective, it is in each prisoner’s best interest to defect as they have the opportunity to go free with the other party serving 3 years if other party stays silent. However, as both prisoners are likely to pursue this self-interested option, they are collectively worse off, with each prisoner receiving 2 years in jail. Had they cooperated and remained silent, they would have each served only 1 year in jail, the best possible combined outcome.
The Fed Prisoner’s Dilemma
Many market participants today are faced with a similar dilemma, and they have become prisoners, in recent months, to Federal Reserve policy. After five and a half years of 0% interest rates and three rounds of QE, returns on virtually all asset classes have been pulled forward. This is precisely what the Fed intended to happen as Ben Bernanke made clear in his famous “wealth effect” Op-ed in 2010.
It is debatable whether there has indeed been a “virtuous circle” as Bernanke suggested, where higher stock prices were supposed to “spur spending” and “lead to higher incomes and profits.”
What is not debatable is that bond yields are at/near all-time lows while stock prices are near valuation highs. This suggests that forward returns from here are likely to be significantly below average. As such, market participants are becoming increasingly reliant on the Federal Reserve to maintain the status quo, and to not pullback from unprecedented measures even five years into a recovery. For if asset prices are elevated in large part because interest rates are artificially low, it stands to reason that if interest rates are no longer held down asset prices will have to fall.
The dilemma today is as follows. We know that the end of QE3 is fast approaching in October, as the Fed indicated in its most recent minutes. We also know that following the end of QE1 in 2010 and QE2 in 2011 we saw correction of 17% and 21% respectively in the S&P 500.
PD2
It is impossible to quantify how much of a premium the market is trading at with the psychological support of QE underneath it, but let’s assume based on the action in 2010 and 2011 that it is at least 15% higher than it would otherwise be.
Now, we know that institutional investors are not oblivious to this and we also know that they understand that valuations are getting stretched at current levels. In a recent poll of investors, Bloomberg found that 47% of those surveyed believed the equity market was close to “unsustainable levels” while 14% already saw a “bubble.” In the high yield bond market, it the results were even more alarming, with 70% of those surveyed saying the rally in junk-rated bonds was “in a bubble or close to one.”
PD3
Source: Bloomberg Poll
Two Hedge Fund Managers Walk into a Bar
Say we have two hedge fund managers and they are the only active market participants: Hedge Fund Manager A, let’s call him Davy Tepper, and Hedge Fund Manager B, let’s call him Billy Ackman.
Davy and Billy are both heavily long equities and well versed in QE and what happened in 2010 and 2011. While they are both still very bullish on equities, they do not like drawdowns and neither do their investors. They are aware of each other’s existence but are isolated in the sense that they don’t speak to one another before they make a trade.
What are their options here with the equity markets at all-time highs and the end of QE fast approaching? They can 1) remain heavily long (dance until the music stops) and wait until the end of QE to sell, or 2) cheat and sell early while the music is still playing.
A theoretical payoff diagram is below. If Davy and Billy cooperate and stay long, they can have a nice, orderly sell-off at the end of QE with a 5% drawdown. However, Davy doesn’t like 5% drawdowns and neither does Billy. They both would prefer a 0% drawdown and have the other fund suffer a 15% drawdown. They would look like heroes in that scenario. By acting in their own self-interest and selling early, though, they will end up suffering more than had they cooperated, each incurring a 10% drawdown.
PD4
Now I realize that this is a wild hypothetical and many ridiculous assumptions are involved, but let’s think this through for a second.
If one wanted to cheat and sell early what would be the main risk? A market that continued to move higher whereby one would miss out on gains, of course. As we all know, the cardinal sin in hedge fund investing is missing out on upside, even it’s in the very short term. If everyone is down and you’re down too, that’s fine; but if you’re flat when everyone else is up that’s a one-way ticket back to the sell-side.
How to Keep Dancing Without Going to Cash
Is there a way that one can sell early without suffering the consequences if the market continues to rally for some time? Sure, by subtly adjusting one’s beta, or reducing one’s risk. And if I wanted to reduce risk without other funds knowing about it, I would do three things:
1) Move out of more illiquid/higher beta small and micro caps and more liquid/lower beta large caps,
2) Move out of more cyclical sectors like Financials and Consumer Discretionary and into more defensive sectors such as Utilities, and
3) Move into one of the most defensive asset classes, long duration Treasuries.
If we look at the markets in 2014 we can clearly see that many funds are likely already cheating in some form.
First, as I wrote about last week, there is a glaring divergence between large and small cap stocks, with the S&P 500 and Dow still hitting new all-time highs while the Russell 2000 and Russell Microcap indices are down YTD.
PD5
PD6
Second, we are seeing classic late cycle behavior within sectors, with the defensive Utilities sector outperforming while the cyclical Financials and Consumer Discretionary sectors are underperforming. As I wrote about last week, this behavior bears an uncanny resemblance to July 2007.
PD7
Lastly, we are seeing a persistent bid in one of the most defensive asset classes: long duration Treasuries (TLT).
PD8
Not only are they outpacing US equities YTD, but the yield curve has been flattening the entire year, an additional signal of defensiveness within the Treasury market.
PD9
One Foot out the Door
Whether you subscribe to my  Fed game theory or not,  it is important  to recognize what the market is telling us. In no uncertain terms, the big money investors are already preparing for more difficult times ahead with “one foot out the door” rotations into lower beta areas of the market. They may not be going to cash as they still fear missing upside, but they are certainly not going to wait for the end of QE to reduce risk in their portfolios.
Many investors will disregard this message that the market is sending, as they are probably thinking that they are like Drukenmiller and “can get out in a week.” Perhaps, but if the events following 2000 and 2007 have taught us anything, investors are much more likely to overstay their welcome than to sell early. There is now only 100 days left until the Fed’s October meeting where they are expected to announce the end of QE. What will you do?

Lunch is for wimps

Lunch is for wimps
It's not a question of enough, pal. It's a zero sum game, somebody wins, somebody loses. Money itself isn't lost or made, it's simply transferred from one perception to another.